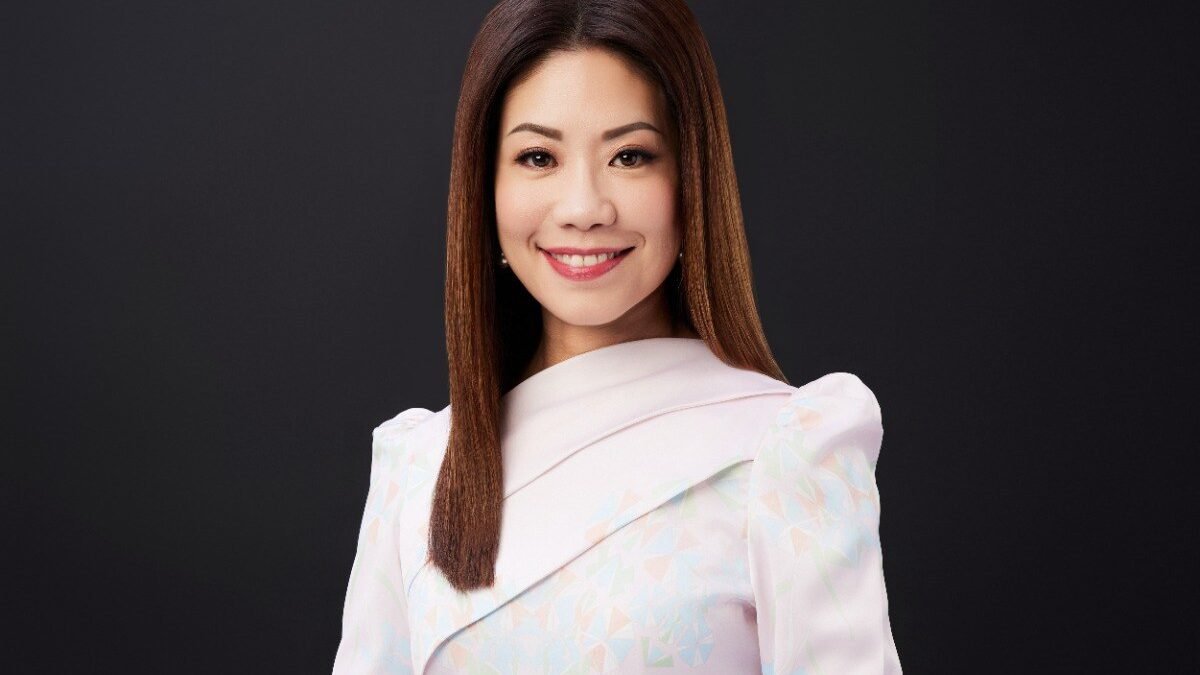
Malaysia attracted RM218.5 billion in approved investments in the first half of 2026, up 11.7% from a year earlier, according to the Malaysian Investment Development Authority (MIDA). Yet UOB Malaysia CEO Datuk Ng Wei Wei argues that headline investment numbers tell only part of the story. Speaking on 6 October 2026, Ng said the more pressing challenge is converting approved capital into deeper local supply chains, higher-value employment and genuine participation by Malaysian companies in the industries those investments represent.
“Attracting investment is only the beginning. The greater opportunity lies in ensuring these investments create broader economic benefit by strengthening supply chains, creating quality jobs and enabling local businesses to participate in higher-value activities,” Ng said. Her remarks align with a structural concern that Bank Negara Malaysia has also identified: backward linkages — the share of foreign inputs embedded in Malaysia’s exports — account for around 34% of gross exports, meaning a substantial portion of export value is created outside the country before it reaches Malaysian factories.
Three Gaps Between Investment Approval and Industrial Benefit
Ng identified three structural areas where Malaysia needs to do more work if approved investments are to deliver lasting economic benefit rather than headline figures alone.
- Skilled talent: Demand for engineers, technicians and specialised professionals is rising alongside rapid growth in semiconductors, artificial intelligence and digital infrastructure. Ng said Malaysia needs to strengthen its talent base so domestic companies can access and participate in higher-value activities.
- Local supply chain depth: A stronger domestic supply chain ecosystem allows Malaysian companies to benefit from foreign investments through technology transfer, talent development and innovation, rather than remaining peripheral service providers to anchor investors.
- Policy and regulatory consistency: Businesses and long-term investors require policy predictability, efficient execution and regulatory clarity. Ng said these conditions matter as much as the initial investment incentive when companies are deciding where to commit capital for five to ten years.
What the Data Shows: Investment Scale Versus Domestic Value Capture
| Indicator | Figure | Period / Source |
|---|---|---|
| MIDA approved investments | RM218.5 billion | H1 2026; MIDA |
| Year-on-year growth in approvals | +11.7% | H1 2026 vs H1 2025; MIDA |
| Approved investments (Q1 2026 alone) | ~RM93 billion | Q1 2026; UOB Malaysia / MIDA |
| Foreign value added in Malaysia’s gross exports (backward linkages) | ~34% | 2022 data; Bank Negara Malaysia EMR 2025 |
| Export-oriented manufacturing employment | ~1.3 million workers | Bank Negara Malaysia EMR 2025 |
| Manufacturing wages as share of total manufacturing wages | ~58% | Bank Negara Malaysia EMR 2025 |
| Malaysia IMD World Competitiveness Ranking 2026 | 15th (up 8 places) | 2026; Institute for Management Development |
| UOB-facilitated FDI into JS-SEZ since 2024 | More than RM20 billion | As of October 2026; UOB Malaysia |
Bank Negara Malaysia’s Economic and Monetary Review 2025 notes that while Malaysia’s domestic value added (DVA) intensity has risen modestly across most manufacturing sectors between 2010 and 2022, the electrical and electronics (E&E) industry remains heavily reliant on foreign intermediate inputs. E&E accounts for the largest share of foreign value added in Malaysia’s exports, reflecting a production model in which components and sub-assemblies cross borders multiple times before reaching final demand. The central bank’s analysis is explicit: DVA — the portion of an export that contributes to Malaysian GDP and wages — is a stronger channel for turning export growth into domestic income than gross export volume alone.
Bridging the Gap: From Policy Framework to Supply Chain Programmes
Several government frameworks directly address the supply chain participation gap that Ng describes. The New Industrial Master Plan 2030, National Semiconductor Strategy and National Energy Transition Roadmap each contain provisions intended to deepen local industrial capabilities. Malaysia’s improved competitiveness ranking — 15th in the IMD World Competitiveness Ranking 2026, up eight places — strengthens the case for the country as a regional investment platform, though Ng was careful to note that competitiveness rankings improve the odds of attracting investment, not automatically the quality of its downstream effects.
At the sectoral level, MIDA’s inaugural Renewable Energy Supply Chain Programme, held on 8 October 2026 at IGEM 2026 in Kuala Lumpur, is a concrete example of policy being translated into matchmaking. The programme connected TNB Power Generation Sdn. Bhd. (TNB GENCO) and TNB Renewables Sdn. Bhd. (TNB RE) with approximately 25 Malaysian manufacturers, vendors, engineers and service providers. Five companies — Alliance MEP Sdn. Bhd., Reactive Energy Sdn. Bhd., Deltaspec (M) Sdn. Bhd., P.E.S.B. Engineering Sdn. Bhd. and SAA Engineering & Marine Sdn. Bhd. — were recognised as Renewable Energy Local Champions for their technical capabilities.
MIDA CEO Datuk Sikh Shamsul Ibrahim Sikh Abdul Majid framed the programme’s purpose in terms that echo Ng’s wider argument: “Every quality investment we facilitate [should create] meaningful linkages with our domestic industry and [contribute] to the development of a more competitive renewable energy ecosystem.” Budget 2027 measures — including the extension of the Green Investment Tax Allowance (GITA) until 31 December 2030 and a combined RM17 billion directed at grid infrastructure and energy investment funds involving TNB, UEM Lestra and KWAP — are intended to sustain that momentum.
Regional Hotspots: Johor, the Northern Corridor and Sarawak
Ng pointed to distinct regional dynamics that affect how supply chain development plays out across Malaysia. The Johor-Singapore Special Economic Zone (JS-SEZ) has moved from planning into implementation, and UOB says it has facilitated more than RM20 billion in foreign direct investment flows into the zone since 2024 — up from the more than RM18 billion the bank reported in April 2026 — through collaborations with Invest Johor, MIDA and other agencies. UOB signed an MOU with Invest Johor in August 2024 and launched a Green Lane Initiative with Invest Johor in February 2025, alongside a Fast Lane Account Opening service for Singapore-based clients expanding into the JS-SEZ.
Ng described the JS-SEZ’s success as contingent on how seamlessly businesses can operate across both markets: “from setting up operations and managing capital to accessing banking services and growth opportunities.” For that integration to work at an industrial level, Malaysian SMEs and mid-sized companies need both the financial tools and the operational capabilities to become credible supply chain participants, not just passive recipients of foreign capital in their geography.
Beyond Johor, Ng identified the northern corridor — Penang and surrounding states — as a continuing hub for E&E and semiconductors; Selangor as a major destination for advanced manufacturing, aerospace and life sciences; and Sarawak as an emerging green economic corridor, supported by land availability, hydropower resources and policies aimed at attracting green industries.
SMEs Face a Dual Challenge: Capability and Sustainability Compliance
For Malaysian SMEs seeking to enter or advance within semiconductor and electronics supply chains, the operational challenge is compounding. Ng said companies are increasingly required to improve emissions measurement and reporting, supply chain traceability and certification, while also investing in energy-efficient equipment. Meeting these requirements from multinational customers and export markets adds to the cost of doing business even as SMEs are trying to build technical capabilities.
The UOB Business Outlook Study 2026, cited by Ng, found that three in four businesses view energy security and efficiency as a priority — a finding that suggests sustainability compliance is no longer a niche concern but a mainstream operational pressure for companies at most levels of the supply chain.
There is also an important distinction Ng drew regarding credit assessment in a knowledge-based economy. As more companies derive value from intellectual property and technology rather than physical assets, she said UOB’s lending fundamentals have not changed: assessment remains based on “the overall viability of the business, its ability to execute its strategy and its growth prospects.” For local companies seeking supply chain financing, trade finance or working capital to pursue capability upgrades, how they articulate their business model and growth trajectory to lenders is increasingly as important as their collateral position.
What to Watch as the Investment Cycle Matures
Several developments will determine whether Malaysia’s investment surge translates into deeper local industrial participation over the next two to three years. MIDA’s H2 2026 investment approval data, when released, will indicate whether the 11.7% growth rate in approved investments sustained through the first half. The JS-SEZ’s transition from approvals to active operations — which Ng noted can involve a significant lag as companies commit capital ahead of infrastructure readiness — will be a practical test of whether regulatory and banking support can compress that timeline.
MIDA’s #InvestLokal agenda and the Renewable Energy Supply Chain Programme are in early stages; how many of the approximately 25 companies that participated in the October 2026 business-matching sessions convert initial contacts into confirmed project roles will signal whether structured matchmaking can systematically raise local supply chain participation. The GITA extension to end-2030 gives renewable energy investors a confirmed incentive window, but domestic companies will need to demonstrate the technical capabilities to benefit from it. Malaysia’s IMD ranking improvement provides a favourable signal for attracting the next wave of investors; the harder policy task, as Ng’s comments make clear, is ensuring that wave does more for domestic industry than the last.