Why the Macro Data Has Not Caught Up
Bank Negara Malaysia’s Economic and Monetary Review 2025 projects Malaysia’s real GDP growth at 4%–5% for 2026, supported by firm labour market conditions, realisation of approved investment projects and continued semiconductor exports. Headline inflation is forecast between 1.5% and 2.5%. These aggregate indicators do not directly contradict the SME stress described above — sectoral displacement can occur within an economy that is growing at the headline level, particularly when investment flows are concentrated in large-scale foreign-anchored manufacturing rather than domestically embedded SME activity.
The BNM review’s own box article on global value chain participation notes that Malaysia must position itself as a “reliable, high-value node” within global value chains to thrive in a geopolitically fragmented environment — an ambition that requires a functioning domestic industrial base, not merely foreign-investment enclave capacity. Malaysia’s GVC participation rate of 55% of gross exports already exceeds the global average of 48.9%, according to OECD Trade in Value Added 2025 edition data cited in the BNM review. Preserving the domestic SME layer is directly relevant to whether that participation generates lasting wage and productivity gains or remains concentrated at the enclave level.
What to Watch
Several near-term indicators will reveal how quickly the stress visible at the business level translates into measurable economic data:
- Post-Chinese New Year retail closures: The analysis cites retailer announcements of closures after the holiday period as a concrete leading signal. Confirmation or scale of these closures will indicate whether the stress is concentrated or broad-based.
- Miti trade remedy activity: Whether the ministry activates fast-track anti-dumping mechanisms or forms a proactive sector-monitoring task force under Act 504 will determine whether the policy response moves ahead of further capacity destruction.
- Steel sector utilisation data: Misif capacity utilisation figures for 2026 will indicate if the below-50% long-steel utilisation rate described in the analysis has stabilised or deteriorated further.
- SME tax and fiscal measures in Budget 2027: Any reduction in the SME preferential corporate tax rate or expansion of Accelerated Capital Allowances would signal that the government is shifting its SME support posture from subsidy programmes toward structural competitiveness reform.
- E-commerce customs enforcement: Progress on closing the low-value goods tax arbitrage gap — or a decision to take the more direct approach adopted by Indonesia — will indicate the government’s appetite for protecting domestic retail supply chains.
The analysis was published as a Forum piece in The Edge Malaysia Weekly (12–18 October 2026). Its author, Shamsul Saad, is national organisation bureau chief of Parti Bangsa Malaysia and a former group managing director of Perdana Petroleum Bhd. The claims and policy proposals represent the author’s analysis and should be read as an informed assessment rather than confirmed government or regulatory positions.
What Policy Reform Would Need to Address
The analysis does not argue for blanket protectionism. It argues for calibrated enforcement of trade integrity and a reorientation of economic success metrics away from headline foreign direct investment inflows toward net domestic value-add. The specific measures proposed cover five areas:
- Trade remedy reform under Act 504: The Ministry of Investment, Trade and Industry (Miti) should strengthen the Countervailing and Anti-Dumping Duties Act 1993, moving beyond provisional 60-day duty mechanisms to establish an active task force that identifies vulnerable sectors and prevents tariff circumvention before domestic capacity is destroyed.
- Customs parity on cross-border e-commerce: Streamline import duty frameworks so that foreign digital platforms and local business owners operate under equivalent tax treatment.
- Mandatory local procurement and wage benchmarks: Link foreign industrial manufacturing licences to a minimum 60% local vendor allocation and benchmarked salary structures for domestic technical hires, ensuring capital inflows generate measurable local economic spillovers.
- SME fiscal relief: Reduce the preferential corporate income tax rate for local SMEs from 15% to 10% on taxable income up to RM600,000, expand 100% Accelerated Capital Allowances to support automation, and work toward a systemically low overall corporate tax ceiling for the private sector.
- Supply-side deregulation: Reduce operational costs by removing tolls and protective concessions in domestic logistics, port handling and energy supply, and reduce administrative compliance burdens — specifically citing the Business Reporting System and Income Tax Reporting System as wasteful overhead for SMEs with no productivity return.
The analysis also calls for deregulation of Malaysia’s financial industry to expand SME access to funding, arguing that current restrictions protect GLIC investment positions at the expense of the domestic private sector’s liquidity.
Why the Macro Data Has Not Caught Up
Bank Negara Malaysia’s Economic and Monetary Review 2025 projects Malaysia’s real GDP growth at 4%–5% for 2026, supported by firm labour market conditions, realisation of approved investment projects and continued semiconductor exports. Headline inflation is forecast between 1.5% and 2.5%. These aggregate indicators do not directly contradict the SME stress described above — sectoral displacement can occur within an economy that is growing at the headline level, particularly when investment flows are concentrated in large-scale foreign-anchored manufacturing rather than domestically embedded SME activity.
The BNM review’s own box article on global value chain participation notes that Malaysia must position itself as a “reliable, high-value node” within global value chains to thrive in a geopolitically fragmented environment — an ambition that requires a functioning domestic industrial base, not merely foreign-investment enclave capacity. Malaysia’s GVC participation rate of 55% of gross exports already exceeds the global average of 48.9%, according to OECD Trade in Value Added 2025 edition data cited in the BNM review. Preserving the domestic SME layer is directly relevant to whether that participation generates lasting wage and productivity gains or remains concentrated at the enclave level.
What to Watch
Several near-term indicators will reveal how quickly the stress visible at the business level translates into measurable economic data:
- Post-Chinese New Year retail closures: The analysis cites retailer announcements of closures after the holiday period as a concrete leading signal. Confirmation or scale of these closures will indicate whether the stress is concentrated or broad-based.
- Miti trade remedy activity: Whether the ministry activates fast-track anti-dumping mechanisms or forms a proactive sector-monitoring task force under Act 504 will determine whether the policy response moves ahead of further capacity destruction.
- Steel sector utilisation data: Misif capacity utilisation figures for 2026 will indicate if the below-50% long-steel utilisation rate described in the analysis has stabilised or deteriorated further.
- SME tax and fiscal measures in Budget 2027: Any reduction in the SME preferential corporate tax rate or expansion of Accelerated Capital Allowances would signal that the government is shifting its SME support posture from subsidy programmes toward structural competitiveness reform.
- E-commerce customs enforcement: Progress on closing the low-value goods tax arbitrage gap — or a decision to take the more direct approach adopted by Indonesia — will indicate the government’s appetite for protecting domestic retail supply chains.
The analysis was published as a Forum piece in The Edge Malaysia Weekly (12–18 October 2026). Its author, Shamsul Saad, is national organisation bureau chief of Parti Bangsa Malaysia and a former group managing director of Perdana Petroleum Bhd. The claims and policy proposals represent the author’s analysis and should be read as an informed assessment rather than confirmed government or regulatory positions.
Digital Retail and the De Minimis Problem
The same pressure that displaced Malaysian steelmakers is now visible in light manufacturing, wholesale distribution and commercial services through a different channel: ultra-low-cost direct-from-factory e-commerce.
Malaysia introduced a 10% low value goods sales tax on imported goods priced below RM500, but cross-border sellers have continued to exploit customs tariff structures and direct-shipping subsidies. Local bricks-and-mortar retailers carry commercial property leases, regulatory compliance costs and standard import tariffs on bulk stock — a structural cost disadvantage that the tax measure alone has not resolved. Indonesia has responded more decisively by blocking Temu (operated by Pinduoduo parent PDD Holdings) outright to protect its domestic micro, small and medium enterprise sector.
A related property dynamic compounds the retail pressure: Chinese-linked businesses with large cash reserves have been acquiring commercial real estate, inflating industrial land valuations and raising fixed operational overheads for Malaysian operators across F&B, automotive services and light manufacturing — sectors that cannot easily absorb higher occupancy costs under already compressed margins.
What Policy Reform Would Need to Address
The analysis does not argue for blanket protectionism. It argues for calibrated enforcement of trade integrity and a reorientation of economic success metrics away from headline foreign direct investment inflows toward net domestic value-add. The specific measures proposed cover five areas:
- Trade remedy reform under Act 504: The Ministry of Investment, Trade and Industry (Miti) should strengthen the Countervailing and Anti-Dumping Duties Act 1993, moving beyond provisional 60-day duty mechanisms to establish an active task force that identifies vulnerable sectors and prevents tariff circumvention before domestic capacity is destroyed.
- Customs parity on cross-border e-commerce: Streamline import duty frameworks so that foreign digital platforms and local business owners operate under equivalent tax treatment.
- Mandatory local procurement and wage benchmarks: Link foreign industrial manufacturing licences to a minimum 60% local vendor allocation and benchmarked salary structures for domestic technical hires, ensuring capital inflows generate measurable local economic spillovers.
- SME fiscal relief: Reduce the preferential corporate income tax rate for local SMEs from 15% to 10% on taxable income up to RM600,000, expand 100% Accelerated Capital Allowances to support automation, and work toward a systemically low overall corporate tax ceiling for the private sector.
- Supply-side deregulation: Reduce operational costs by removing tolls and protective concessions in domestic logistics, port handling and energy supply, and reduce administrative compliance burdens — specifically citing the Business Reporting System and Income Tax Reporting System as wasteful overhead for SMEs with no productivity return.
The analysis also calls for deregulation of Malaysia’s financial industry to expand SME access to funding, arguing that current restrictions protect GLIC investment positions at the expense of the domestic private sector’s liquidity.
Why the Macro Data Has Not Caught Up
Bank Negara Malaysia’s Economic and Monetary Review 2025 projects Malaysia’s real GDP growth at 4%–5% for 2026, supported by firm labour market conditions, realisation of approved investment projects and continued semiconductor exports. Headline inflation is forecast between 1.5% and 2.5%. These aggregate indicators do not directly contradict the SME stress described above — sectoral displacement can occur within an economy that is growing at the headline level, particularly when investment flows are concentrated in large-scale foreign-anchored manufacturing rather than domestically embedded SME activity.
The BNM review’s own box article on global value chain participation notes that Malaysia must position itself as a “reliable, high-value node” within global value chains to thrive in a geopolitically fragmented environment — an ambition that requires a functioning domestic industrial base, not merely foreign-investment enclave capacity. Malaysia’s GVC participation rate of 55% of gross exports already exceeds the global average of 48.9%, according to OECD Trade in Value Added 2025 edition data cited in the BNM review. Preserving the domestic SME layer is directly relevant to whether that participation generates lasting wage and productivity gains or remains concentrated at the enclave level.
What to Watch
Several near-term indicators will reveal how quickly the stress visible at the business level translates into measurable economic data:
- Post-Chinese New Year retail closures: The analysis cites retailer announcements of closures after the holiday period as a concrete leading signal. Confirmation or scale of these closures will indicate whether the stress is concentrated or broad-based.
- Miti trade remedy activity: Whether the ministry activates fast-track anti-dumping mechanisms or forms a proactive sector-monitoring task force under Act 504 will determine whether the policy response moves ahead of further capacity destruction.
- Steel sector utilisation data: Misif capacity utilisation figures for 2026 will indicate if the below-50% long-steel utilisation rate described in the analysis has stabilised or deteriorated further.
- SME tax and fiscal measures in Budget 2027: Any reduction in the SME preferential corporate tax rate or expansion of Accelerated Capital Allowances would signal that the government is shifting its SME support posture from subsidy programmes toward structural competitiveness reform.
- E-commerce customs enforcement: Progress on closing the low-value goods tax arbitrage gap — or a decision to take the more direct approach adopted by Indonesia — will indicate the government’s appetite for protecting domestic retail supply chains.
The analysis was published as a Forum piece in The Edge Malaysia Weekly (12–18 October 2026). Its author, Shamsul Saad, is national organisation bureau chief of Parti Bangsa Malaysia and a former group managing director of Perdana Petroleum Bhd. The claims and policy proposals represent the author’s analysis and should be read as an informed assessment rather than confirmed government or regulatory positions.
Steel: The First Industrial Casualty
The iron and steel sector is the most documented case of what this dynamic produces in practice. According to Malaysian Iron and Steel Industry Federation (Misif) data cited in the analysis, national apparent steel consumption runs between 7.5 million and 9.5 million tonnes annually. Domestic production capacity, however, has expanded to more than 24 million tonnes, driven primarily by large-scale foreign-backed projects.
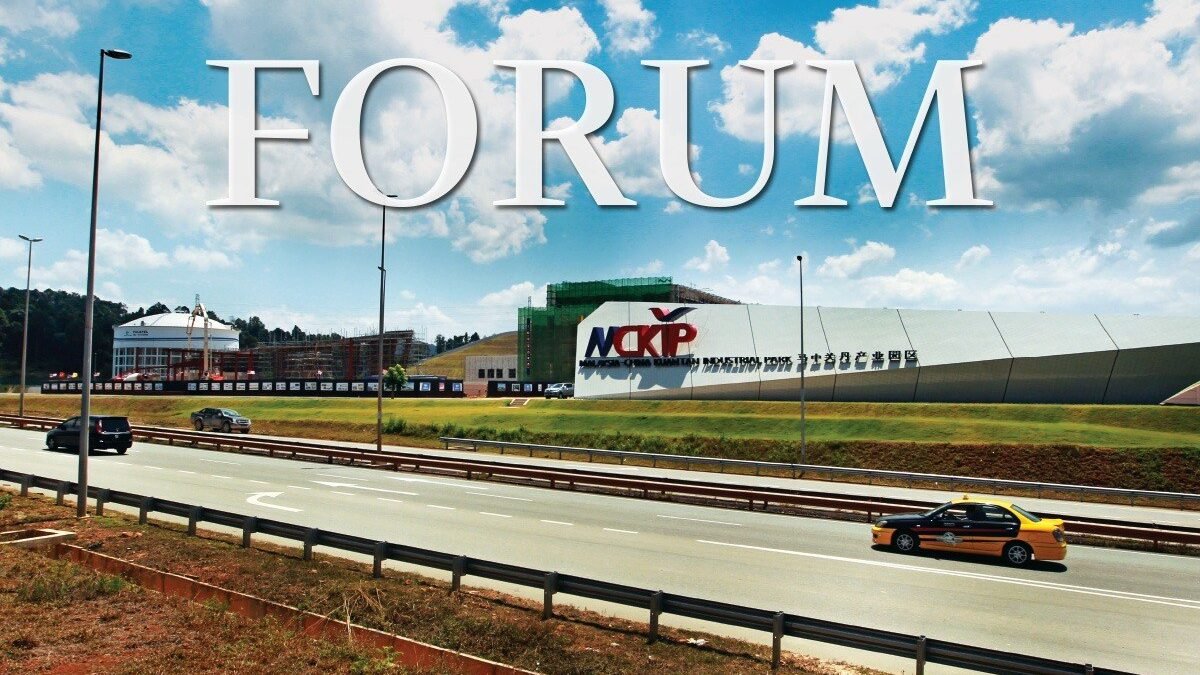
The establishment of integrated steel complexes in the Malaysia-China Kuantan Industrial Park — including Alliance Steel (M) Sdn Bhd — introduced substantial new capacity into an already saturated regional market. The consequences for incumbent Malaysian producers were severe:
- Domestic long-steel capacity utilisation fell below 50%, well beneath the 70%–80% threshold required for cash break-even operations.
- Established Malaysian producers including Kinsteel Bhd and Perwaja Steel Sdn Bhd faced severe balance sheet distress, forced restructurings or liquidation.
- Local re-rollers without sovereign debt backstops could not sustain operations at below-cost market pricing.
- The foreign-backed complexes operate as industrial enclaves, importing machinery, technical services and feedstock directly from China and minimising or eliminating local procurement — removing the economic multipliers and domestic wage spillovers that previous investment models generated.
The analysis points out that fellow ASEAN and BRICS economies — including Brazil, Indonesia and Vietnam — have enacted anti-dumping duties and strict local content mandates in comparable situations. Malaysia, by contrast, has offered attractive land deals and investment incentives to projects that have demonstrably compressed domestic capacity utilisation and forced out locally funded competitors.
Digital Retail and the De Minimis Problem
The same pressure that displaced Malaysian steelmakers is now visible in light manufacturing, wholesale distribution and commercial services through a different channel: ultra-low-cost direct-from-factory e-commerce.
Malaysia introduced a 10% low value goods sales tax on imported goods priced below RM500, but cross-border sellers have continued to exploit customs tariff structures and direct-shipping subsidies. Local bricks-and-mortar retailers carry commercial property leases, regulatory compliance costs and standard import tariffs on bulk stock — a structural cost disadvantage that the tax measure alone has not resolved. Indonesia has responded more decisively by blocking Temu (operated by Pinduoduo parent PDD Holdings) outright to protect its domestic micro, small and medium enterprise sector.
A related property dynamic compounds the retail pressure: Chinese-linked businesses with large cash reserves have been acquiring commercial real estate, inflating industrial land valuations and raising fixed operational overheads for Malaysian operators across F&B, automotive services and light manufacturing — sectors that cannot easily absorb higher occupancy costs under already compressed margins.
What Policy Reform Would Need to Address
The analysis does not argue for blanket protectionism. It argues for calibrated enforcement of trade integrity and a reorientation of economic success metrics away from headline foreign direct investment inflows toward net domestic value-add. The specific measures proposed cover five areas:
- Trade remedy reform under Act 504: The Ministry of Investment, Trade and Industry (Miti) should strengthen the Countervailing and Anti-Dumping Duties Act 1993, moving beyond provisional 60-day duty mechanisms to establish an active task force that identifies vulnerable sectors and prevents tariff circumvention before domestic capacity is destroyed.
- Customs parity on cross-border e-commerce: Streamline import duty frameworks so that foreign digital platforms and local business owners operate under equivalent tax treatment.
- Mandatory local procurement and wage benchmarks: Link foreign industrial manufacturing licences to a minimum 60% local vendor allocation and benchmarked salary structures for domestic technical hires, ensuring capital inflows generate measurable local economic spillovers.
- SME fiscal relief: Reduce the preferential corporate income tax rate for local SMEs from 15% to 10% on taxable income up to RM600,000, expand 100% Accelerated Capital Allowances to support automation, and work toward a systemically low overall corporate tax ceiling for the private sector.
- Supply-side deregulation: Reduce operational costs by removing tolls and protective concessions in domestic logistics, port handling and energy supply, and reduce administrative compliance burdens — specifically citing the Business Reporting System and Income Tax Reporting System as wasteful overhead for SMEs with no productivity return.
The analysis also calls for deregulation of Malaysia’s financial industry to expand SME access to funding, arguing that current restrictions protect GLIC investment positions at the expense of the domestic private sector’s liquidity.
Why the Macro Data Has Not Caught Up
Bank Negara Malaysia’s Economic and Monetary Review 2025 projects Malaysia’s real GDP growth at 4%–5% for 2026, supported by firm labour market conditions, realisation of approved investment projects and continued semiconductor exports. Headline inflation is forecast between 1.5% and 2.5%. These aggregate indicators do not directly contradict the SME stress described above — sectoral displacement can occur within an economy that is growing at the headline level, particularly when investment flows are concentrated in large-scale foreign-anchored manufacturing rather than domestically embedded SME activity.
The BNM review’s own box article on global value chain participation notes that Malaysia must position itself as a “reliable, high-value node” within global value chains to thrive in a geopolitically fragmented environment — an ambition that requires a functioning domestic industrial base, not merely foreign-investment enclave capacity. Malaysia’s GVC participation rate of 55% of gross exports already exceeds the global average of 48.9%, according to OECD Trade in Value Added 2025 edition data cited in the BNM review. Preserving the domestic SME layer is directly relevant to whether that participation generates lasting wage and productivity gains or remains concentrated at the enclave level.
What to Watch
Several near-term indicators will reveal how quickly the stress visible at the business level translates into measurable economic data:
- Post-Chinese New Year retail closures: The analysis cites retailer announcements of closures after the holiday period as a concrete leading signal. Confirmation or scale of these closures will indicate whether the stress is concentrated or broad-based.
- Miti trade remedy activity: Whether the ministry activates fast-track anti-dumping mechanisms or forms a proactive sector-monitoring task force under Act 504 will determine whether the policy response moves ahead of further capacity destruction.
- Steel sector utilisation data: Misif capacity utilisation figures for 2026 will indicate if the below-50% long-steel utilisation rate described in the analysis has stabilised or deteriorated further.
- SME tax and fiscal measures in Budget 2027: Any reduction in the SME preferential corporate tax rate or expansion of Accelerated Capital Allowances would signal that the government is shifting its SME support posture from subsidy programmes toward structural competitiveness reform.
- E-commerce customs enforcement: Progress on closing the low-value goods tax arbitrage gap — or a decision to take the more direct approach adopted by Indonesia — will indicate the government’s appetite for protecting domestic retail supply chains.
The analysis was published as a Forum piece in The Edge Malaysia Weekly (12–18 October 2026). Its author, Shamsul Saad, is national organisation bureau chief of Parti Bangsa Malaysia and a former group managing director of Perdana Petroleum Bhd. The claims and policy proposals represent the author’s analysis and should be read as an informed assessment rather than confirmed government or regulatory positions.
Malaysian small and medium enterprises across retail, construction, food and beverage, automotive services and light manufacturing are facing a structural threat that goes beyond normal competitive pressure. According to an analysis published in The Edge Malaysia on 12 October 2026, the primary driver is China’s systematic redirection of state-subsidised industrial and commercial overcapacity into export markets — including Malaysia — as its domestic real estate-led growth model continues to contract. The author, Shamsul Saad, a former group managing director of Perdana Petroleum Bhd, argues that the resulting market distortion cannot be corrected by operational efficiency improvements alone and that official macroeconomic data has yet to fully capture the damage already under way.
The warning carries weight precisely because it is not sector-specific. When businesses across construction supply chains, F&B outlets, mechanics’ workshops and retail simultaneously report margin compression, slowing customer traffic, rising costs and impossibly low price competition from Chinese-linked operators, the pattern points to a systemic cause rather than isolated business failures. Shamsul notes that many retailers have already stated they will close after Chinese New Year — a concrete leading indicator that official surveys have not yet registered.
Why China Is Exporting Its Surplus Now
China’s structural position is the starting point for understanding what Malaysian SMEs are facing. China’s gross national savings rate sits at approximately 43% to 45% of GDP — roughly double the global average — while domestic consumption remains relatively weak despite the country generating around 30% of global manufacturing output. The collapse of its property sector, led by Evergrande and Country Garden accumulating approximately US$500 billion (RM2.04 trillion) in combined liabilities, has removed the main channel through which household wealth was accumulated and internal capital was deployed.
With internal real estate investment contracting, state-backed capital has been redirected into industrial manufacturing output. Lacking sufficient domestic absorption, subsidised excess production — spanning heavy industrial goods, solar photovoltaic modules, consumer retail products and, increasingly, services — is routed outward. Provincial officials, whose political performance is measured against GDP growth targets, have strong structural incentives to maintain output regardless of global demand.
The Scale Gap Malaysian Businesses Cannot Close
The competitive asymmetry is not simply about lower wages or state subsidies. It is fundamentally a question of scale that no individual Malaysian enterprise or industry can match.
| Metric | China | Malaysia | Comparison |
|---|---|---|---|
| Active workforce | ~725 million | ~17.3 million (DOSM) | China’s workforce is approximately 42× Malaysia’s |
| Urban employed population | ~470 million | — | At 5% unemployment, ~23.5 million urban Chinese are unemployed — exceeding Malaysia’s entire workforce |
| Urban private sector median monthly wage (China) | RMB4,500–RMB4,800 (~RM2,745–RM2,930) | RM3,065 formal sector median (DOSM) | Malaysian and Chinese baseline wages are functionally comparable |
| Provinces with workforce >30 million | 11 provinces (Guangxi ~30m to Guangdong ~70m) | — | Each province alone rivals or exceeds Malaysia’s total labour pool |
| EU active labour force | — | — | ~195 million (for scale reference) |
| US active labour force | — | — | ~168 million (for scale reference) |
Sources: Analysis citing China National Bureau of Statistics wage data and DOSM labour market figures, as reported in The Edge Malaysia, 12 October 2026.
Because China’s baseline urban wage and Malaysia’s formal sector median wage are functionally on par, Malaysian SMEs cannot rely on labour cost advantages to offset China’s industrial scale, integrated provincial supply clusters or state-backed capital efficiencies. Malaysian businesses borrow at commercial rates, pay statutory taxes and comply with domestic regulations. Competing foreign-linked entities operating under sovereign liquidity mandates that prioritise market share over return on capital face an entirely different cost structure.
Steel: The First Industrial Casualty
The iron and steel sector is the most documented case of what this dynamic produces in practice. According to Malaysian Iron and Steel Industry Federation (Misif) data cited in the analysis, national apparent steel consumption runs between 7.5 million and 9.5 million tonnes annually. Domestic production capacity, however, has expanded to more than 24 million tonnes, driven primarily by large-scale foreign-backed projects.
The establishment of integrated steel complexes in the Malaysia-China Kuantan Industrial Park — including Alliance Steel (M) Sdn Bhd — introduced substantial new capacity into an already saturated regional market. The consequences for incumbent Malaysian producers were severe:
- Domestic long-steel capacity utilisation fell below 50%, well beneath the 70%–80% threshold required for cash break-even operations.
- Established Malaysian producers including Kinsteel Bhd and Perwaja Steel Sdn Bhd faced severe balance sheet distress, forced restructurings or liquidation.
- Local re-rollers without sovereign debt backstops could not sustain operations at below-cost market pricing.
- The foreign-backed complexes operate as industrial enclaves, importing machinery, technical services and feedstock directly from China and minimising or eliminating local procurement — removing the economic multipliers and domestic wage spillovers that previous investment models generated.
The analysis points out that fellow ASEAN and BRICS economies — including Brazil, Indonesia and Vietnam — have enacted anti-dumping duties and strict local content mandates in comparable situations. Malaysia, by contrast, has offered attractive land deals and investment incentives to projects that have demonstrably compressed domestic capacity utilisation and forced out locally funded competitors.
Digital Retail and the De Minimis Problem
The same pressure that displaced Malaysian steelmakers is now visible in light manufacturing, wholesale distribution and commercial services through a different channel: ultra-low-cost direct-from-factory e-commerce.
Malaysia introduced a 10% low value goods sales tax on imported goods priced below RM500, but cross-border sellers have continued to exploit customs tariff structures and direct-shipping subsidies. Local bricks-and-mortar retailers carry commercial property leases, regulatory compliance costs and standard import tariffs on bulk stock — a structural cost disadvantage that the tax measure alone has not resolved. Indonesia has responded more decisively by blocking Temu (operated by Pinduoduo parent PDD Holdings) outright to protect its domestic micro, small and medium enterprise sector.
A related property dynamic compounds the retail pressure: Chinese-linked businesses with large cash reserves have been acquiring commercial real estate, inflating industrial land valuations and raising fixed operational overheads for Malaysian operators across F&B, automotive services and light manufacturing — sectors that cannot easily absorb higher occupancy costs under already compressed margins.
What Policy Reform Would Need to Address
The analysis does not argue for blanket protectionism. It argues for calibrated enforcement of trade integrity and a reorientation of economic success metrics away from headline foreign direct investment inflows toward net domestic value-add. The specific measures proposed cover five areas:
- Trade remedy reform under Act 504: The Ministry of Investment, Trade and Industry (Miti) should strengthen the Countervailing and Anti-Dumping Duties Act 1993, moving beyond provisional 60-day duty mechanisms to establish an active task force that identifies vulnerable sectors and prevents tariff circumvention before domestic capacity is destroyed.
- Customs parity on cross-border e-commerce: Streamline import duty frameworks so that foreign digital platforms and local business owners operate under equivalent tax treatment.
- Mandatory local procurement and wage benchmarks: Link foreign industrial manufacturing licences to a minimum 60% local vendor allocation and benchmarked salary structures for domestic technical hires, ensuring capital inflows generate measurable local economic spillovers.
- SME fiscal relief: Reduce the preferential corporate income tax rate for local SMEs from 15% to 10% on taxable income up to RM600,000, expand 100% Accelerated Capital Allowances to support automation, and work toward a systemically low overall corporate tax ceiling for the private sector.
- Supply-side deregulation: Reduce operational costs by removing tolls and protective concessions in domestic logistics, port handling and energy supply, and reduce administrative compliance burdens — specifically citing the Business Reporting System and Income Tax Reporting System as wasteful overhead for SMEs with no productivity return.
The analysis also calls for deregulation of Malaysia’s financial industry to expand SME access to funding, arguing that current restrictions protect GLIC investment positions at the expense of the domestic private sector’s liquidity.
Why the Macro Data Has Not Caught Up
Bank Negara Malaysia’s Economic and Monetary Review 2025 projects Malaysia’s real GDP growth at 4%–5% for 2026, supported by firm labour market conditions, realisation of approved investment projects and continued semiconductor exports. Headline inflation is forecast between 1.5% and 2.5%. These aggregate indicators do not directly contradict the SME stress described above — sectoral displacement can occur within an economy that is growing at the headline level, particularly when investment flows are concentrated in large-scale foreign-anchored manufacturing rather than domestically embedded SME activity.
The BNM review’s own box article on global value chain participation notes that Malaysia must position itself as a “reliable, high-value node” within global value chains to thrive in a geopolitically fragmented environment — an ambition that requires a functioning domestic industrial base, not merely foreign-investment enclave capacity. Malaysia’s GVC participation rate of 55% of gross exports already exceeds the global average of 48.9%, according to OECD Trade in Value Added 2025 edition data cited in the BNM review. Preserving the domestic SME layer is directly relevant to whether that participation generates lasting wage and productivity gains or remains concentrated at the enclave level.
What to Watch
Several near-term indicators will reveal how quickly the stress visible at the business level translates into measurable economic data:
- Post-Chinese New Year retail closures: The analysis cites retailer announcements of closures after the holiday period as a concrete leading signal. Confirmation or scale of these closures will indicate whether the stress is concentrated or broad-based.
- Miti trade remedy activity: Whether the ministry activates fast-track anti-dumping mechanisms or forms a proactive sector-monitoring task force under Act 504 will determine whether the policy response moves ahead of further capacity destruction.
- Steel sector utilisation data: Misif capacity utilisation figures for 2026 will indicate if the below-50% long-steel utilisation rate described in the analysis has stabilised or deteriorated further.
- SME tax and fiscal measures in Budget 2027: Any reduction in the SME preferential corporate tax rate or expansion of Accelerated Capital Allowances would signal that the government is shifting its SME support posture from subsidy programmes toward structural competitiveness reform.
- E-commerce customs enforcement: Progress on closing the low-value goods tax arbitrage gap — or a decision to take the more direct approach adopted by Indonesia — will indicate the government’s appetite for protecting domestic retail supply chains.
The analysis was published as a Forum piece in The Edge Malaysia Weekly (12–18 October 2026). Its author, Shamsul Saad, is national organisation bureau chief of Parti Bangsa Malaysia and a former group managing director of Perdana Petroleum Bhd. The claims and policy proposals represent the author’s analysis and should be read as an informed assessment rather than confirmed government or regulatory positions.